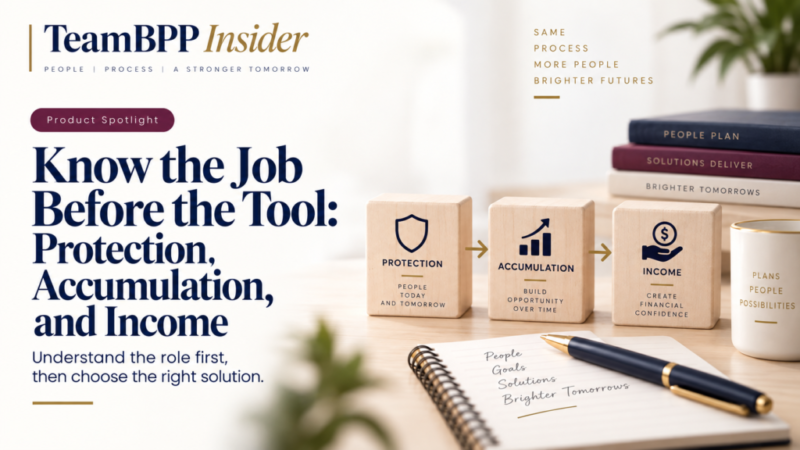
One of the easiest ways to confuse a client is to start with a product name before you have defined the problem.
Products are tools. The first question is not, “Which tool do I like?” The first question is, “What job needs to be done?”
Job One: Protection
Protection asks what happens if life changes unexpectedly.
What income is the household depending on? What debts or responsibilities need to be covered? Who depends on the client? What would happen if illness, disability, or death disrupted the plan?
Different forms of life insurance and available riders can address different protection goals. The recommendation should begin with the need, affordability, suitability, and the client’s full picture—not with a favorite product.
Job Two: Accumulation
Accumulation asks how assets can grow over time and what role liquidity, taxes, risk tolerance, time horizon, and access may play.
Clients may already be using workplace plans, IRAs, brokerage accounts, savings, real estate, insurance-based strategies, or business assets. The job is to understand how the pieces fit together.
An insurance product should not be presented as though every other part of the financial picture disappears.
Job Three: Income
Retirement planning eventually has to answer a different question: how will assets become income?
That means looking at expected Social Security, pensions, workplace plans, other assets, expenses, longevity, taxes, and the need for predictable or flexible income.
Some annuity strategies may be considered for accumulation or income needs depending on the product and client. The point is not that “annuities are the answer.” The point is that income is a specific job that deserves its own analysis.
One Tool Can Do More Than One Job—But That Does Not Mean It Should Do Every Job
Certain products may combine features such as protection and cash-value accumulation, or accumulation and future income options. That can be useful. It can also make explanations more complicated.
Be clear about what the strategy is primarily designed to accomplish, what it does not do, what costs or limitations exist, and what assumptions are being used.
Fit Beats Excitement
A product can be excellent and still be wrong for a particular client.
That is why BPP starts with the financial picture. We want to understand the household, the goals, the risk, the timeline, and the resources before we decide what deserves a closer look.
Stay Inside Your Scope
Insurance professionals should explain insurance and annuity concepts within their license and carrier rules. Tax, legal, and investment questions may require coordination with the appropriate professional.
Professionalism includes knowing where your responsibility ends.
Agent Action Step
For the next recommendation you prepare, write one sentence defining the primary job before you write the product name.
Team Challenge
Practice explaining protection, accumulation, and income in plain language without naming a specific carrier or product.
Team Question
Which job—protection, accumulation, or income—do clients seem to misunderstand most often?